Encyclopedia
Okay.



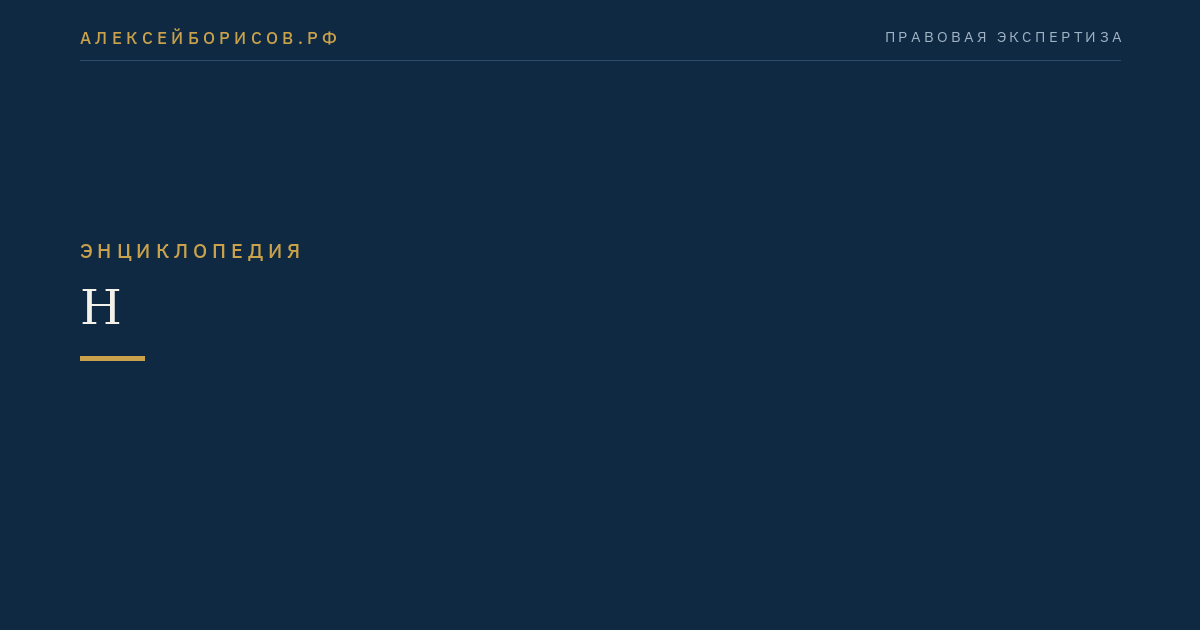
N - the amount of tax on income (profit), calculated by the foreign organization and its separate units in accordance with their own personal law, and the tax on income withheld from the income (profit) of such an organization at the source of payment of such income, unless otherwise provided in paragraph 3 of this paragraph, excluding the tax on income withheld at the source of payment in relation to the income specified in subitem 1 of paragraph 4 of article 309.1 of this Code, the source of payment of which are Russian organizations, if the controlling party of such a foreign organization has actual rights to such income taking into account the provisions of article 312 of this Code1.
N - the amount of tax subject to withholding2.
Tax Code of the Russian Federation. Part one dated 31.07.1998, as amended on 2020-11-09, art. 25.13-1, subitem 1 // RSZ RF. 1998. No. 31. Art. 3824. ↩
Federal Law No. 76-FZ of May 16, 2007, "On Amending Articles 224, 275 and 284 of Part Two of the Tax Code of the Russian Federation," dated May 16, 2007, amended on May 16, 2007, Article 1, subpara. b#2 // RSZ RF. 2007. No. 21. Art. 2462. ↩